Fintech Confidential calls Janna Scott an IRS agent in its March 24, 2026 headline. The introduction describes experience inside the agency, while the guest biography lists an enrolled-agent credential. A customer considering her tax advice has reason to ask which IRS job, if any, the publication is describing.[S01]
“IRS agent” and “enrolled agent” are different claims
Fintech Confidential · March 24, 2026 · Publisher’s wording
In the headline
Crypto Tax Secrets From an IRS Agent Who Audited 14 Platforms
In the main introduction
The article asserts federal-agency experience, including the IRS itself
.
In the guest biography
The credential given is IRS Enrolled Agent
.
Inspect the headline, introduction and guest biography · Source notes
An enrolled agent can represent taxpayers before the IRS. The credential alone does not establish that someone worked for the agency. Applicants can qualify through an examination or through qualifying prior IRS service. To check a claim of federal employment, a buyer needs the position, office and dates of service.[S02]
A former IRS employee and a professional who represents clients before the IRS bring different experience to a tax dispute. Substituting one description for the other can mislead a customer. Which position supports the newsletter’s wording, and who verified it before publication?
The wording belongs to the publisher. The submitted biography and any approval correspondence would help establish Scott’s part in it. The credential comparison places the passages beside the IRS’s explanation of enrollment.
The federal claims changed across the publicity
The employment wording followed a longer publicity campaign. DeFi Tax’s April 2025 release invoked private agency acknowledgment. LA Weekly later attributed an audit-policy decision to the research, and the company’s launch statement described collaboration. The dated comparison identifies who made each claim.[S28][S29][S03]
Those descriptions can affect a buyer’s assessment of the software. The company should identify the officials’ actual contribution and the conclusions they reached. A statement about meeting regulators carries a different meaning from a claim that they helped validate a product.
The Flaunt profile has a publicity trail
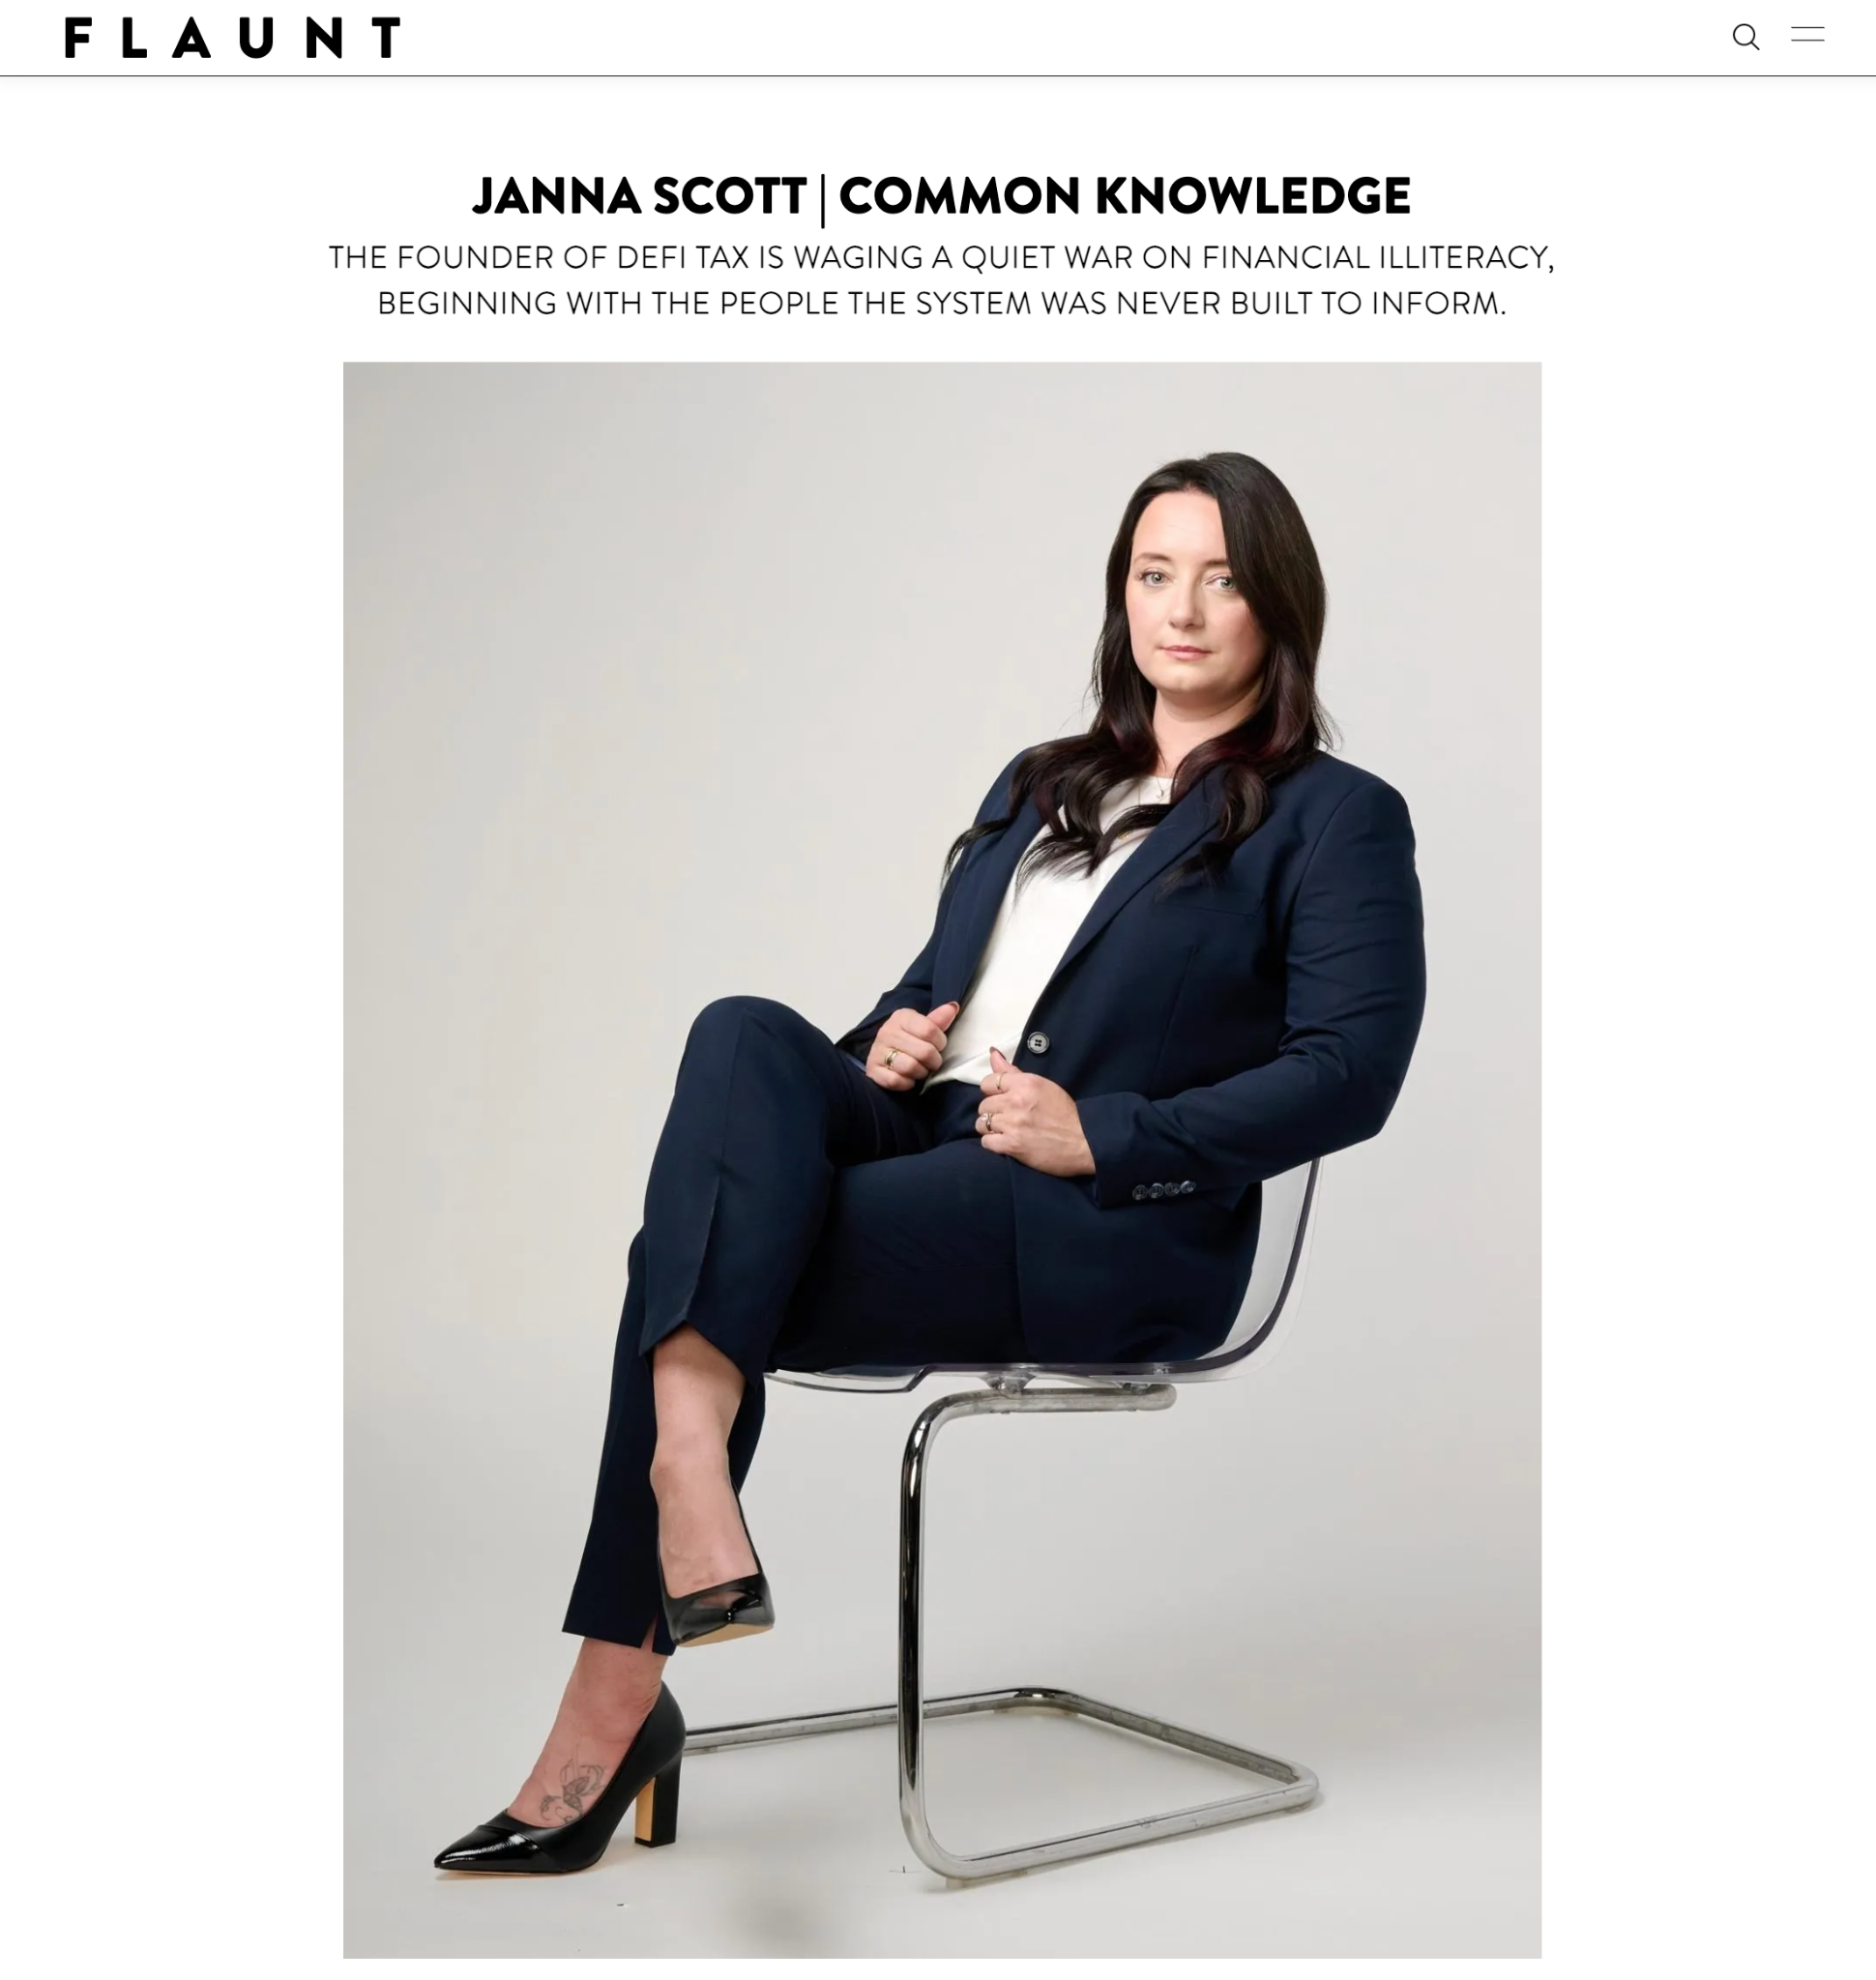
Nelson also appears as the press contact on DeFi Tax’s launch release. His LinkedIn post directs readers to the Flaunt feature and offers a Workhouse contact for media inquiries. Someone encountering both pages is seeing the same publicist promote the founder and her company.[S24][S03]
Imperium advertises a $1,750 Flaunt package: it writes the article, sends it to the customer for approval, then arranges publication. Nextenco advertises a $950 placement. The approval step gives the buyer a say in how the story is told. For Scott’s feature, who commissioned the work, who paid, and which claims did the publisher check?[S16][S17]
The publicity article follows the magazine profile into LinkedIn and explains what the placement vendors sell. It asks how much original reporting lies behind coverage a prospective client might take as independent confirmation of the biography.
The Head Genetics adviser reference
A search-indexed excerpt for a January 30, 2026 discovery plan describes Scott as an adviser to the CAP offering. The federal docket lists the plan as Document 60 in Mark Bianchi’s California case. The filed plan is the record to consult for who supplied that description and the context in which it appears.[S25][S26]
In a separate Delaware complaint, Solidaris and related plaintiffs describe their own donation-based financing model and accuse Head Genetics of copying it for CAP. They allege CAP raised $98 million before the end of 2024. These are allegations by litigants defending a competing commercial offering.[S05]
For a prospective client, the question is what Scott did on that earlier deal. Did she review valuations or participant materials, advise on tax treatment, or assess product readiness? Her assignment and completed work would show the responsibility she accepted. Read the Head Genetics reporting.
What Giving Amplified counts as $1 billion
Giving Amplified’s launch announcement names Scott as a co-founder and values gift-card contributions at $1 billion. Participating businesses receive funding; charities receive rights to products or services.[S08]
The program should account for what donors paid and what charities received. Between those amounts are the credits issued, their assigned value, any fees, and obligations still awaiting redemption. Which amount produces the headline figure? Any deduction offered to participants needs its own calculation.
The Giving Amplified report examines the suppliers’ executive relationships, DeFi Tax’s advertised prices and conditions attached to product delivery. The tax-strategy comparison explains how to test a value above the original purchase price.
Read the audit-protection terms before buying
DeFi Tax lists audit protection as an optional purchase. Its software agreement separately defines the support and liability attached to a subscription. Customers need to know which agreement covers the help being advertised and who must provide it.[S14][S30]
The contract comparison follows those obligations through to donated access. A software license, a promise of representation and professional work already performed have different prices and delivery requirements. Giving Amplified’s accounting should identify which of them contributes to its reported value.
Before paying for the advice
Ask for the employment history behind the introduction and an account of earlier advisory assignments. For a proposed donation strategy, request the valuation and fee schedule before committing money. Another profile or interview does not answer a question about the transaction.
Sources for this article
- S01 Fintech Confidential: published federal-experience claims and credential wordingHeadline; TLDR; main introduction; About The Guest · Source notes
- S02 IRS explanation of enrolled-agent statusEnrolled agent information · Source notes
- S28 DeFi Tax’s April 23, 2025 research releaseParagraph beginning “She adds”; agency meetings and audit claims · Source notes
- S29 LA Weekly: Cracks in Crypto’s Tax SystemThe Architecture of Error; paragraph beginning “Scott brought her findings” · Source notes
- S03 DeFi Tax launch releaseOpening; research claims; media contact · Source notes
- S15 Flaunt profile of ScottProfile and visible article presentation · Source notes
- S24 Adam Nelson’s LinkedIn promotion of the Flaunt profileMain post; Flaunt link; closing Workhouse media contact · Source notes
- S16 Imperium offer for Flaunt placementAdvertised price and approval process · Source notes
- S17 Nextenco offer for Flaunt placementAdvertised sale price and package · Source notes
- S25 CAP adviser reference in the public court-document indexSearch-indexed excerpt for Document 60; 2:25-cv-09741-MEMF-BFM · Source notes
- S26 Bianchi federal case: public docket entry for Document 60January 30, 2026; Filing 60; joint Rule 26(f) discovery plan · Source notes
- S05 Delaware first amended verified complaint2025-1462-MTZ; paragraphs 4–5, 7–12, 33–34, 43 · Source notes
- S08 Giving Amplified launch account reproduced by DNA VibeOpening; founder descriptions; attributed nonprofit comments · Source notes
- S14 DeFi Tax public subscription pricesAnnual tiers; optional add-ons; purchase-before-audit condition · Source notes
- S30 DeFi Tax software subscription agreementOpening; sections 2, 4, 9 and 11 · Source notes